7 Steps to Buying a Home
I’ve created a 7-step checklist to help you understand the home buying process
Step 1: Down Payment
The hardest part to buying a home is saving the down payment (a gift from the Bank of Mom & Dad also works).
- For purchases under $500K, minimum down payment is 5%.
- Buying between $501-999K you need 5% on first $500K PLUS 10% down payment for anything over $500K.
- Buying a home over $1M you need 20% down payment.
For any home purchases with less than 20% down payment, you are also required to purchase Mortgage Default Insurance. BLOG Everything You Wanted to Know about Mortgage Default Insurance
Step 2: Strategize, Define Your Budget and get Pre-Qualified
Unless you can afford to buy a home, cash in hand, you are going to need a mortgage.
You need to get pre-qualified, which should not be confused with the term pre-approved.
The big difference is that no approval is ever given by a lender until they have an opportunity to examine the property that you wish to purchase. The bank may love you… but they also must love the property you want to buy.
Pre-qualifying will focus on gathering documentation to prove the information on your mortgage application including credit, debt load, income/employment, down payment etc.
Mortgage brokers will make sure you get a great mortgage rate. Just as important as rates are the terms of your mortgage which should include:
- prepayment options (10-20%)
- penalties BLOG Mortgage Penalties – Ouch… How Much??
- portability
We also discuss what type of mortgage fits your current situation
- fixed vs variable?
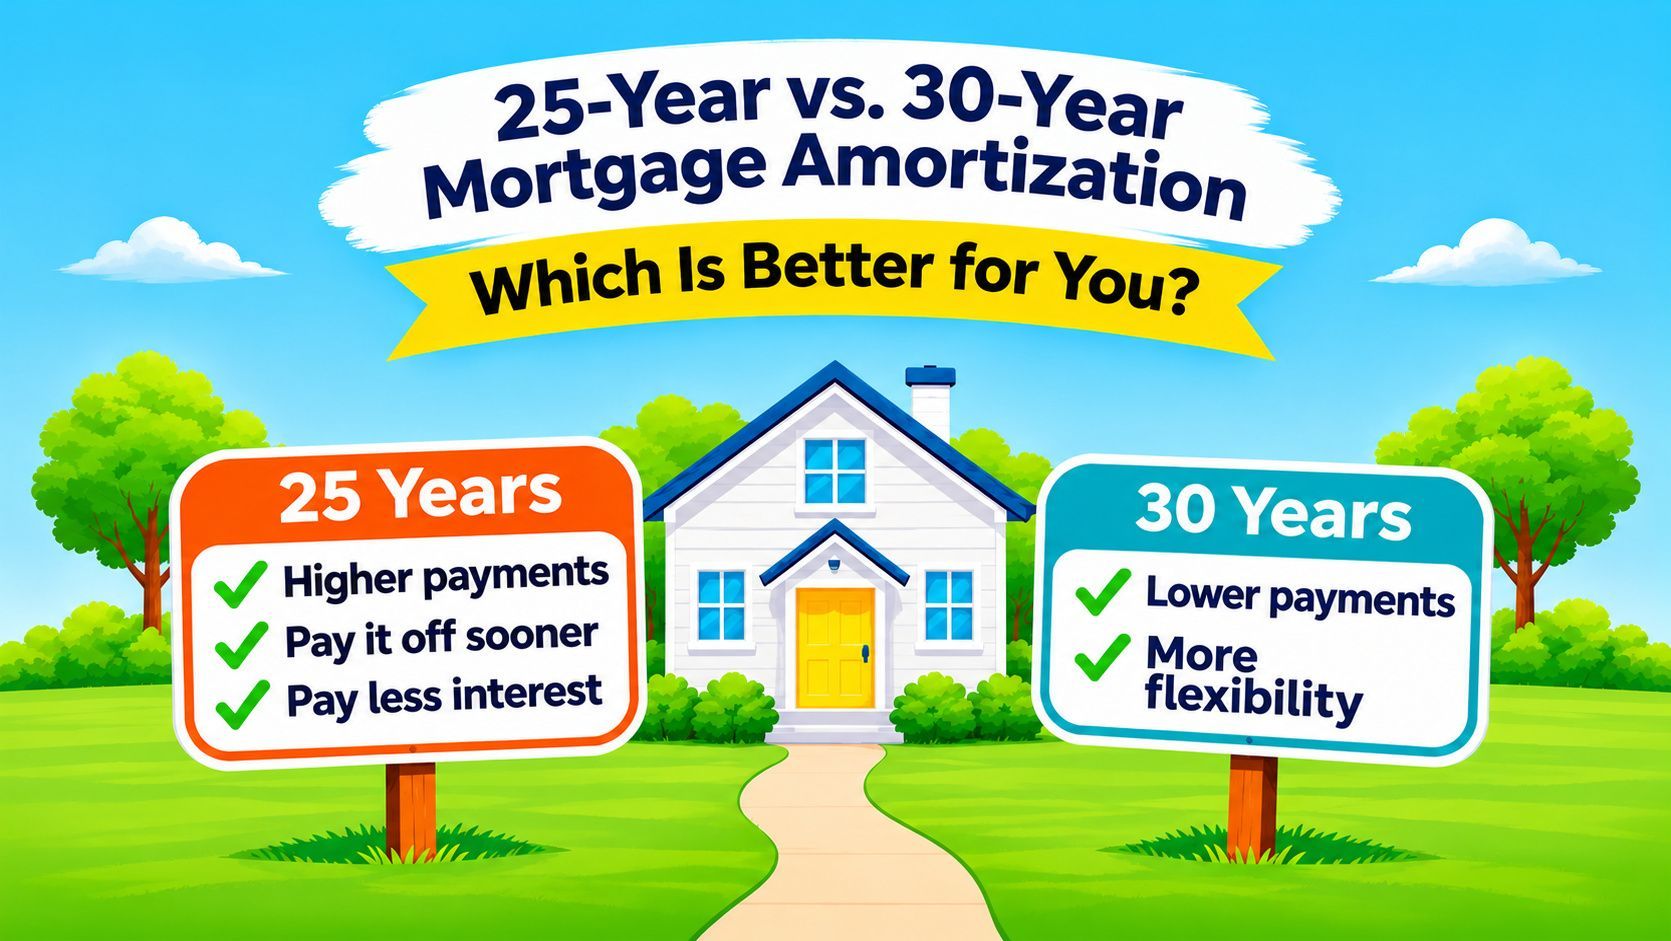
- life of the mortgage (amortization) 25 or 30 years etc.
- payments – monthly, semi monthly, accelerated bi-weekly
Step 3: Set Your Budget
Keep in mind that just because you’re pre-qualified for a certain amount of mortgage, doesn’t mean you can actually afford that amount. Prepare your own monthly budget to be sure.
Typically, your total home payments (including mortgage, property taxes, strata fees & heat) should not exceed 32-39% of your gross (pre-tax) income.
Step 4: Find the Right Property – Time to Engage a Realtor
Once you have been pre-qualified for a mortgage, based on your budget… you need to find a realtor.
Selecting the right real estate agent is a very important step in the home buying process. When you work with an agent, you can expect them to help you with many things, including:
- Finding a home
- Scheduling tours of homes
- Researching the market, neighbourhood and home itself
- Making and negotiating your offer to purchase, and counter-offers
- Providing expert advice on home buying
- Handling the offer, gathering documentation and closing paperwork
I recommend interviewing at least 3 realtors. You will quickly decide who has your best interests in mind. Do you want to deal directly with a realtor who’s going to work with directly when you go home hunting, or do you want to deal with a BIG name realtor, who has buyers & sellers realtors working under them? There are advantages to each – you need to decide what is the best fit for your situation.
Get referrals for realtors from friends and family… OR ask me, I have a group of realtors that I know and trust.
Step 5: Mortgage Approval
Once you have found the property you would like to call home, your mortgage broker will send your mortgage application and property information to the lender who is the best fit for your situation, based on your input.
If the lender likes your financial situation and the property, they will issue a “commitment” letter outlining the terms of the mortgage. The lender will send you a list of documents, so they can verify and validate all the information you told them on the mortgage application.
Step 6: Time for the Solicitor (Lawyer or Notary)
Once the lender has reviewed and approved all your mortgage documentation and the property documentation, your file will be sent to your solicitor (in BC you can use a lawyer or notary). They will process all the necessary title changes and set up a time for you to meet, review mortgage documents and sign.
 Step 7: Get the Keys
On the closing day the documentation for your home purchase will be filed at the land titles office by your solicitor. Typically, the possession date is 1 or 2 days later, giving time for the money (down payment & mortgage) to get to the home seller. On possession day you set up a time to meet with your realtor to get the keys.
Congratulations you’re done – you now own your home!!
Mortgages are complicated, but they don’t have to be… Engage an expert!
Give me a call and let’s discuss a mortgage that works for you (not the bank)!